Me

Professor of Economics
Zicklin School of Business
Baruch College, CUNY
55 Lexington Avenue
New York, NY 10010
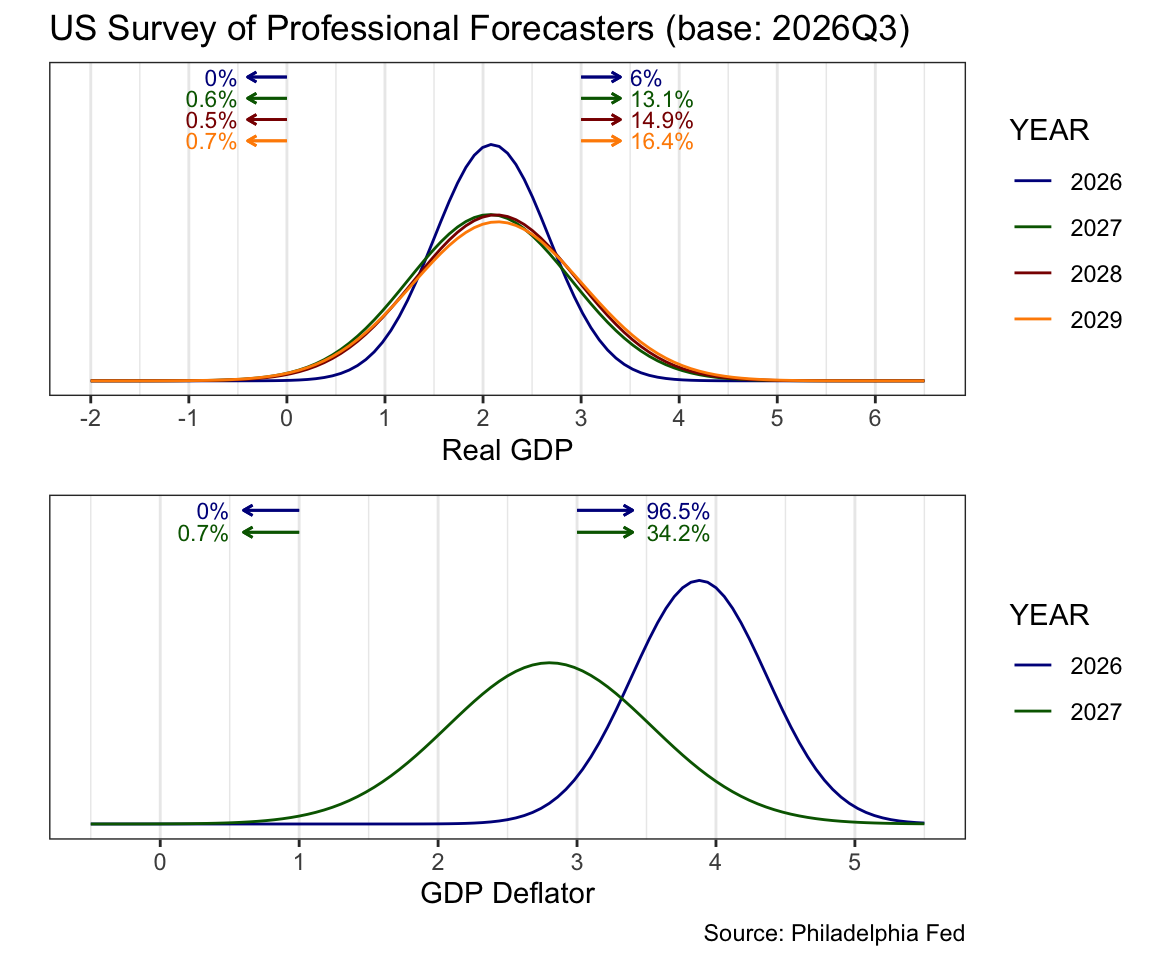
Updated each quarter with the latest survey release.
Research
Working Papers
Publications
Sentiment Analysis of Economic Text: A Lexicon-based Approach, Economic Inquiry (2025), 63, 125-143, with L. Barbaglia, S. Consoli, L. Tiozzo Pezzoli, and E. Tosetti SSRN Lexicon
Household Debt and Economic Growth in Europe, Macroeconomic Dynamics (2025), 29, e10, with L. Barbaglia and E. Tosetti SSRN
Forecasting GDP in Europe with Textual Data, Journal of Applied Econometrics (2024), 39, 338-355, with L. Barbaglia and S. Consoli SSRN R package
Forecasting with Economic News, Journal of Business and Economic Statistics (2023), 41, 708-719, with L. Barbaglia and S. Consoli SSRN Appendix
Forecasting Loan Default in Europe with Machine Learning, Journal of Financial Econometrics (2023), 21, 569-596, with L. Barbaglia and E. Tosetti Journal
Fine-grained, Aspect-based Sentiment Analysis on Economic and Financial Lexicon, Knowledge-Based Systems (2022), 247, 108781, with L. Barbaglia and S. Consoli SSRN
Are Professional Forecasters Bayesian?, Journal of Economic Dynamics and Control (2021), 123 PDF Appendix
Forecasting the Distribution of Economic Variables in a Data-Rich Environment, Journal of Business and Economic Statistics (2015), 33, 144-164 PDF Appendix
Asymmetric Quantile Persistence and Predictability: the Case of U.S. Inflation, Oxford Bulletin of Economics and Statistics (2015), 77, 297-318, with D. Zerom PDF
Forecasting the Return Distribution using High-Frequency Volatility Measures, Journal of Banking and Finance (2013), 37, 4381-4403, with J. Hua PDF
Are Macroeconomic Variables Useful for Forecasting the Distribution of U.S. Inflation?, International Journal of Forecasting (2013), 29, 469-478, with D. Zerom PDF
Differential Interpretation in the Survey of Professional Forecasters, Journal of Money, Credit, and Banking (2011), 43, 993-1017 PDF
U.S. Manufacturing: Productivity, Offshoring, and Imports, Economics Bulletin (2011), 31(4), 2875-2883, with H.N. Ross
A Semiparametric Analysis of Gasoline Demand in the US: Re-examining the Impact of Price, Econometric Reviews (2010), 29, 439-468, with D. Zerom PDF
A Bootstrap-based Nonparametric Forecast Density, International Journal of Forecasting (2008), 24, 535-550, with D. Zerom PDF
Behavioral Heterogeneity in Stock Prices, Journal of Economic Dynamics and Control (2007), 31, 1938-1970, with H.P. Boswijk and C.H. Hommes PDF
Heterogeneous Expectations, Exchange Rate Dynamics and Predictability, Journal of Economic Behavior and Organization (2007), 64, 111-128, with F. Westerhoff PDF
Nonlinear Mean Reversion in Stock Prices, Quantitative and Qualitative Analysis in Social Sciences (2007), 1, 1-20
Testing for Nonlinear Structure and Chaos in Economic Time Series: A Comment, Journal of Macroeconomics (2006), 28, 169-174, with C.H. Hommes PDF
Kernel Estimation of a Partially Linear Additive Model, Statistics and Probability Letters (2005), 72, 313-322, with D. Zerom PDF
Representativeness of News and Exchange Rate Dynamics, Journal of Economic Dynamics and Control (2005), 29, 677-689, with F. Westerhoff PDF
Model Selection for Nonlinear Time Series, Empirical Economics (2004), 29, 901-920 PDF
Does Liquidity in the FX Market Depend on Volatility?, Economics Bulletin (2004), 6(10), with F. Westerhoff
Testing for Serial Independence and Linearity Based on Correlation Integrals, Studies in Nonlinear Dynamics and Econometrics (2002), 6(2), with C.G.H. Diks PDF